Latest from BCA Research
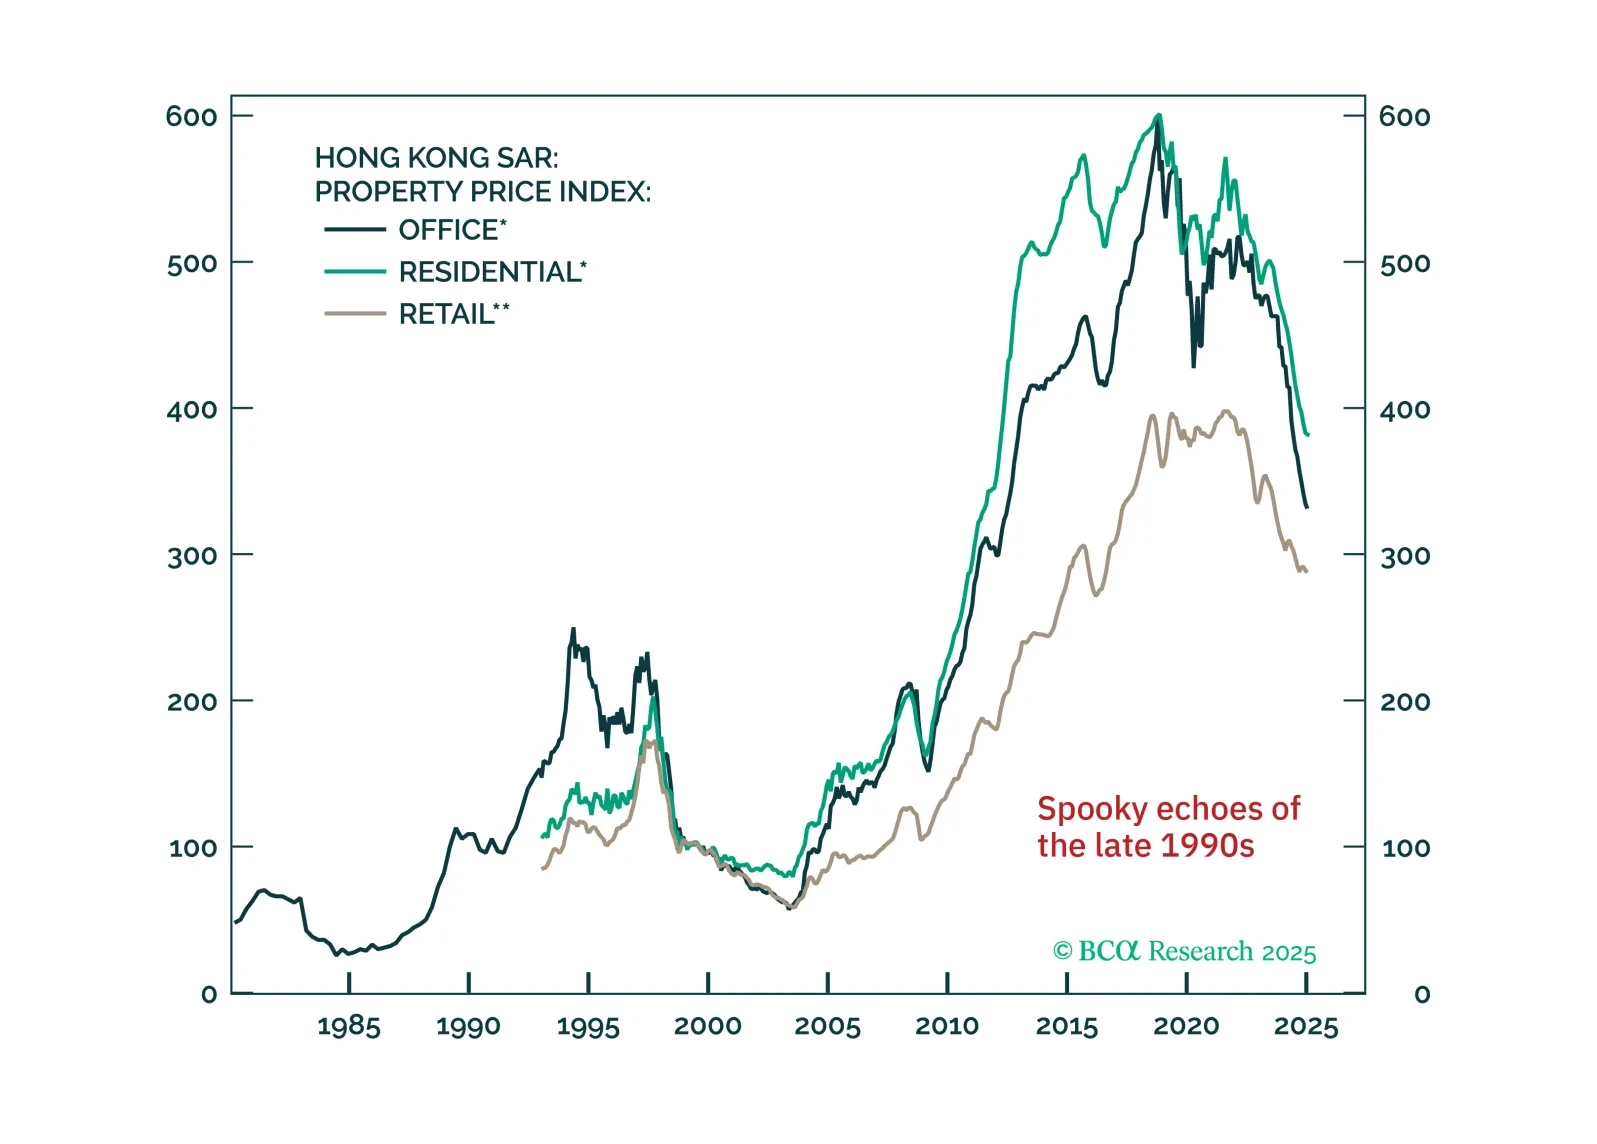
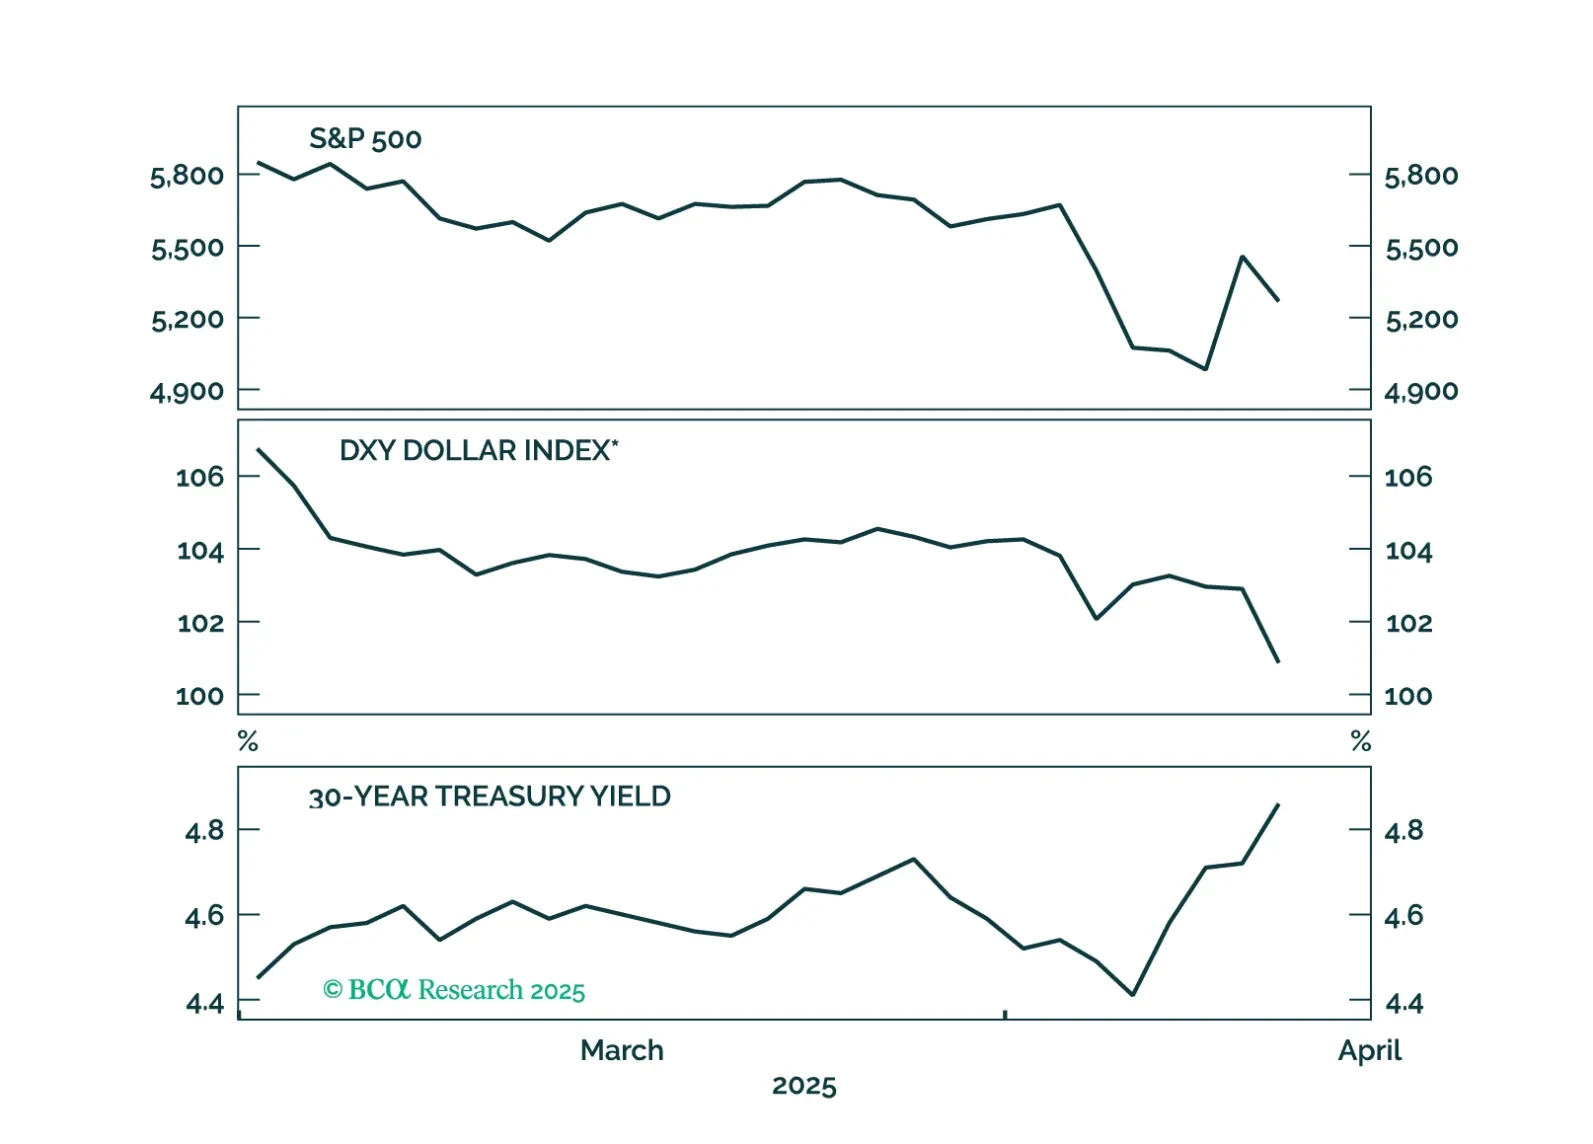
The combination of dollar weakness and rising US yields suggests global investors are questioning the safe-haven status of US Treasuries.

Barring a dramatic further de-escalation of the trade war, the US and much of the rest of the world will enter a recession over the next few months. Investors should remain defensively positioned for now.
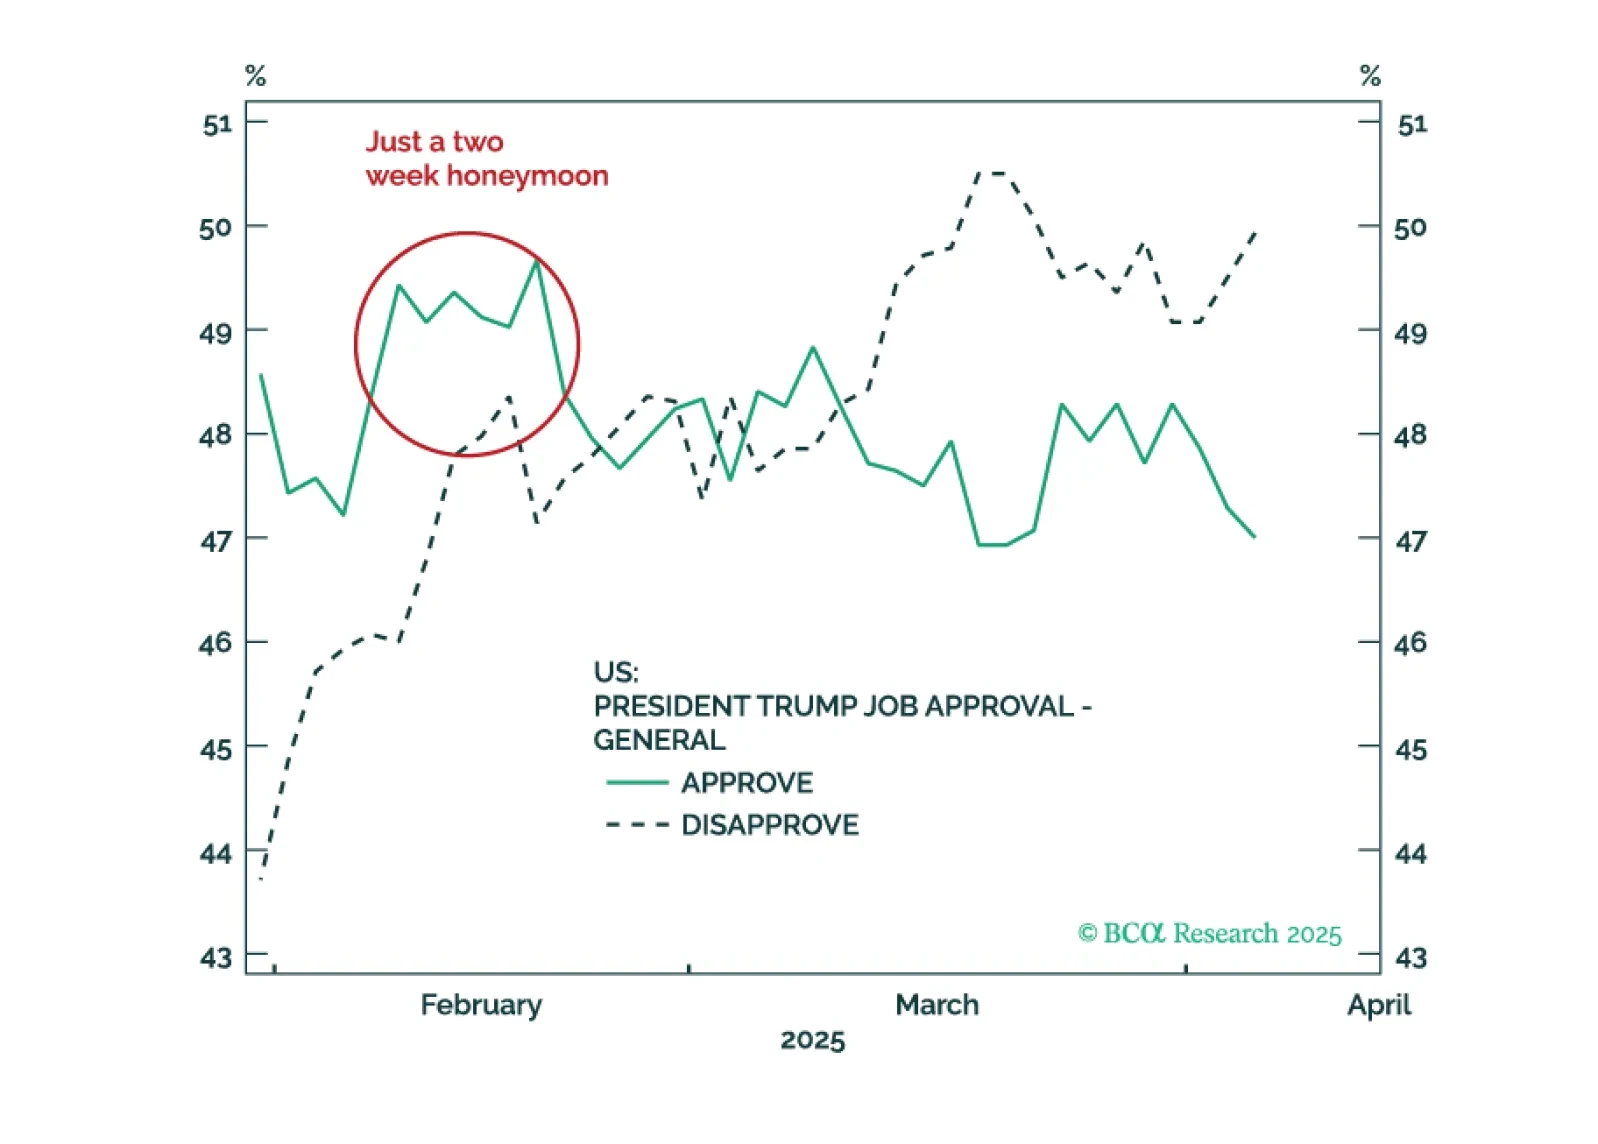
While the market welcomed the pause in Liberation Day tariffs, we believe investors are overly optimistic about the relief from this Trump-driven uncertainty. Even with the pause, current tariff levels remain higher than they were in January. Elevated tariff levels are likely to be inflationary, which could explain the recent spikes in US Treasury yields. Currently, Congress does not have a veto-proof majority to rein in President Trump’s tariff policies, meaning the trade war with China will persist.
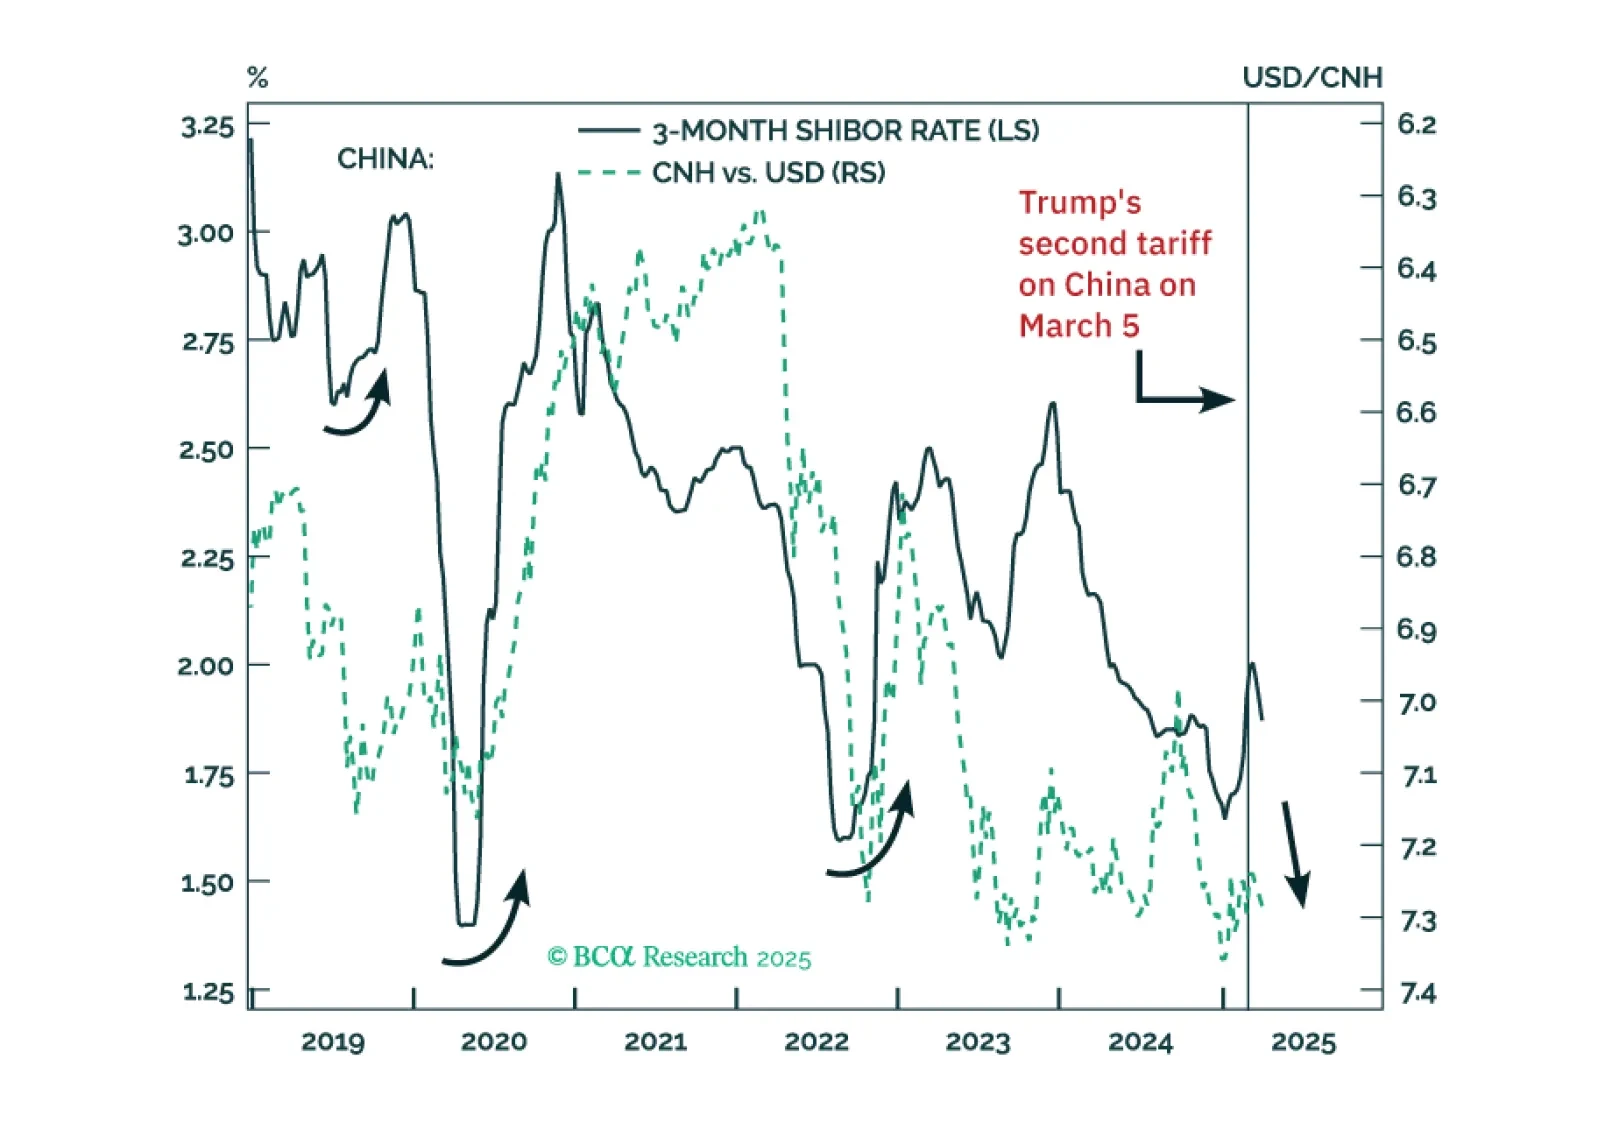
We believe Beijing views these US trade actions as nothing short of a declaration of economic war, not just a trade dispute. The US-China confrontation is set to escalate from here. Chinese authorities will allow the yuan to depreciate materially. Go short CNH against the US dollar. For EM and Asian equity portfolios, we are downgrading Chinese investable/offshore stocks from neutral to underweight.
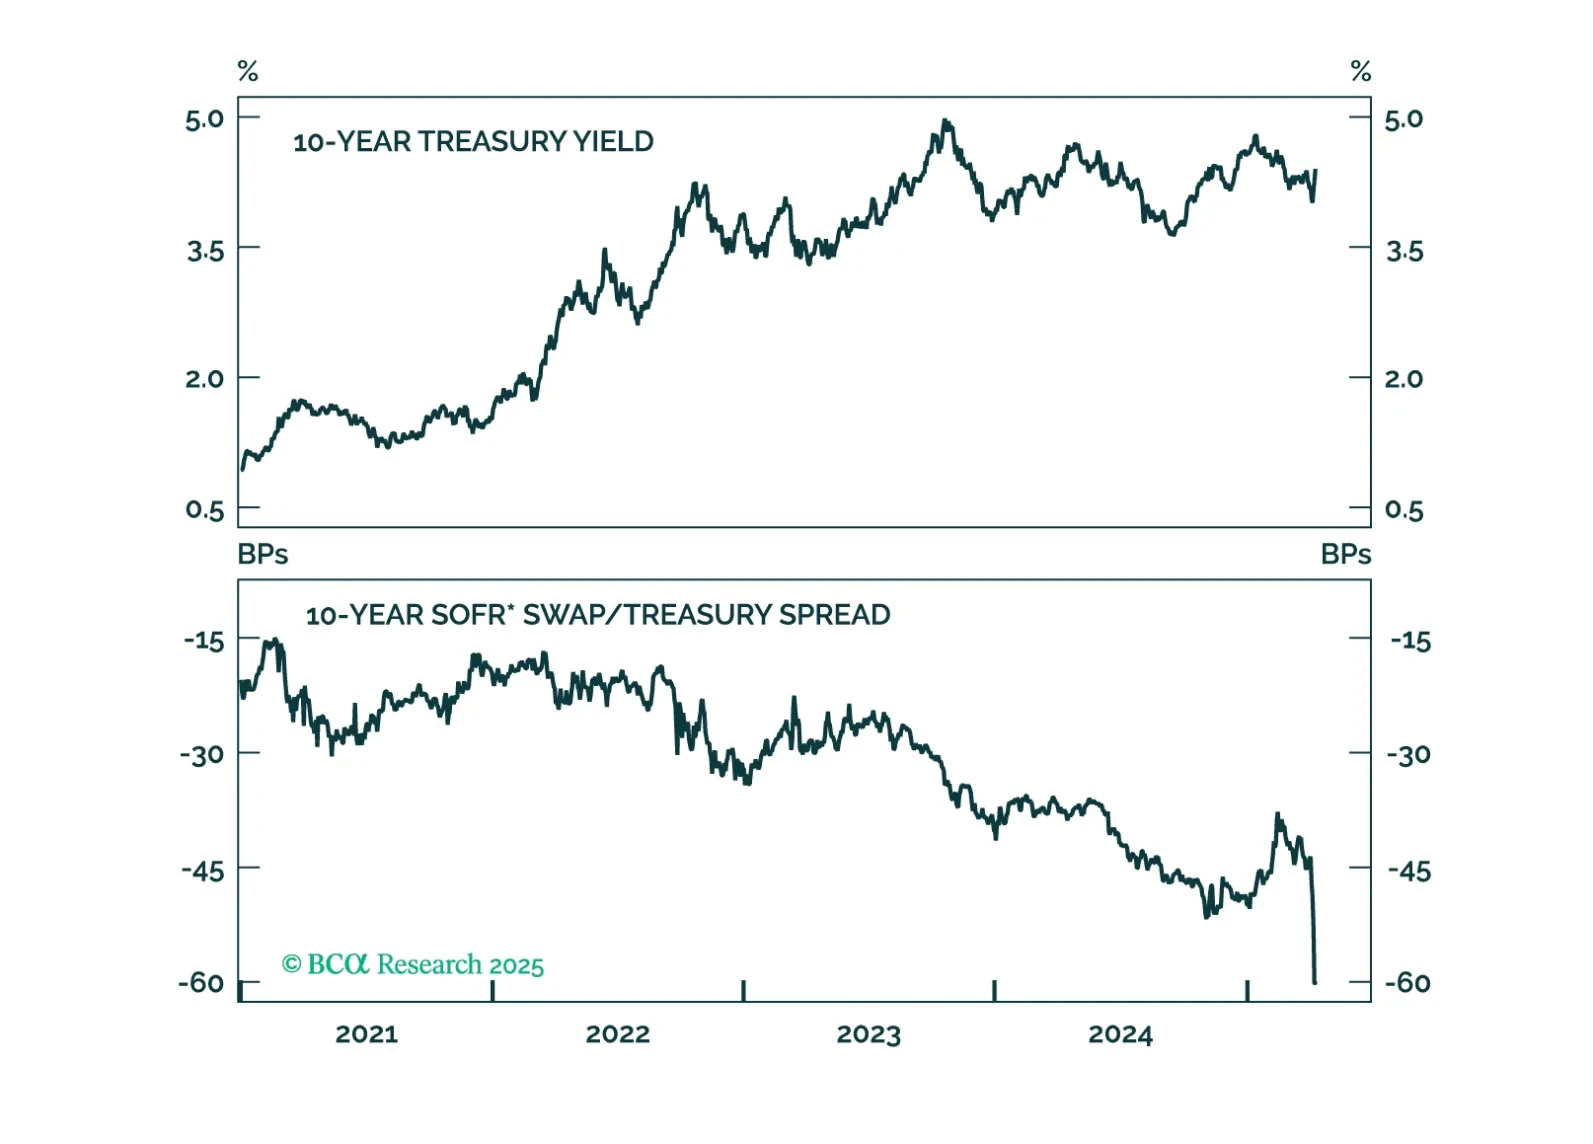
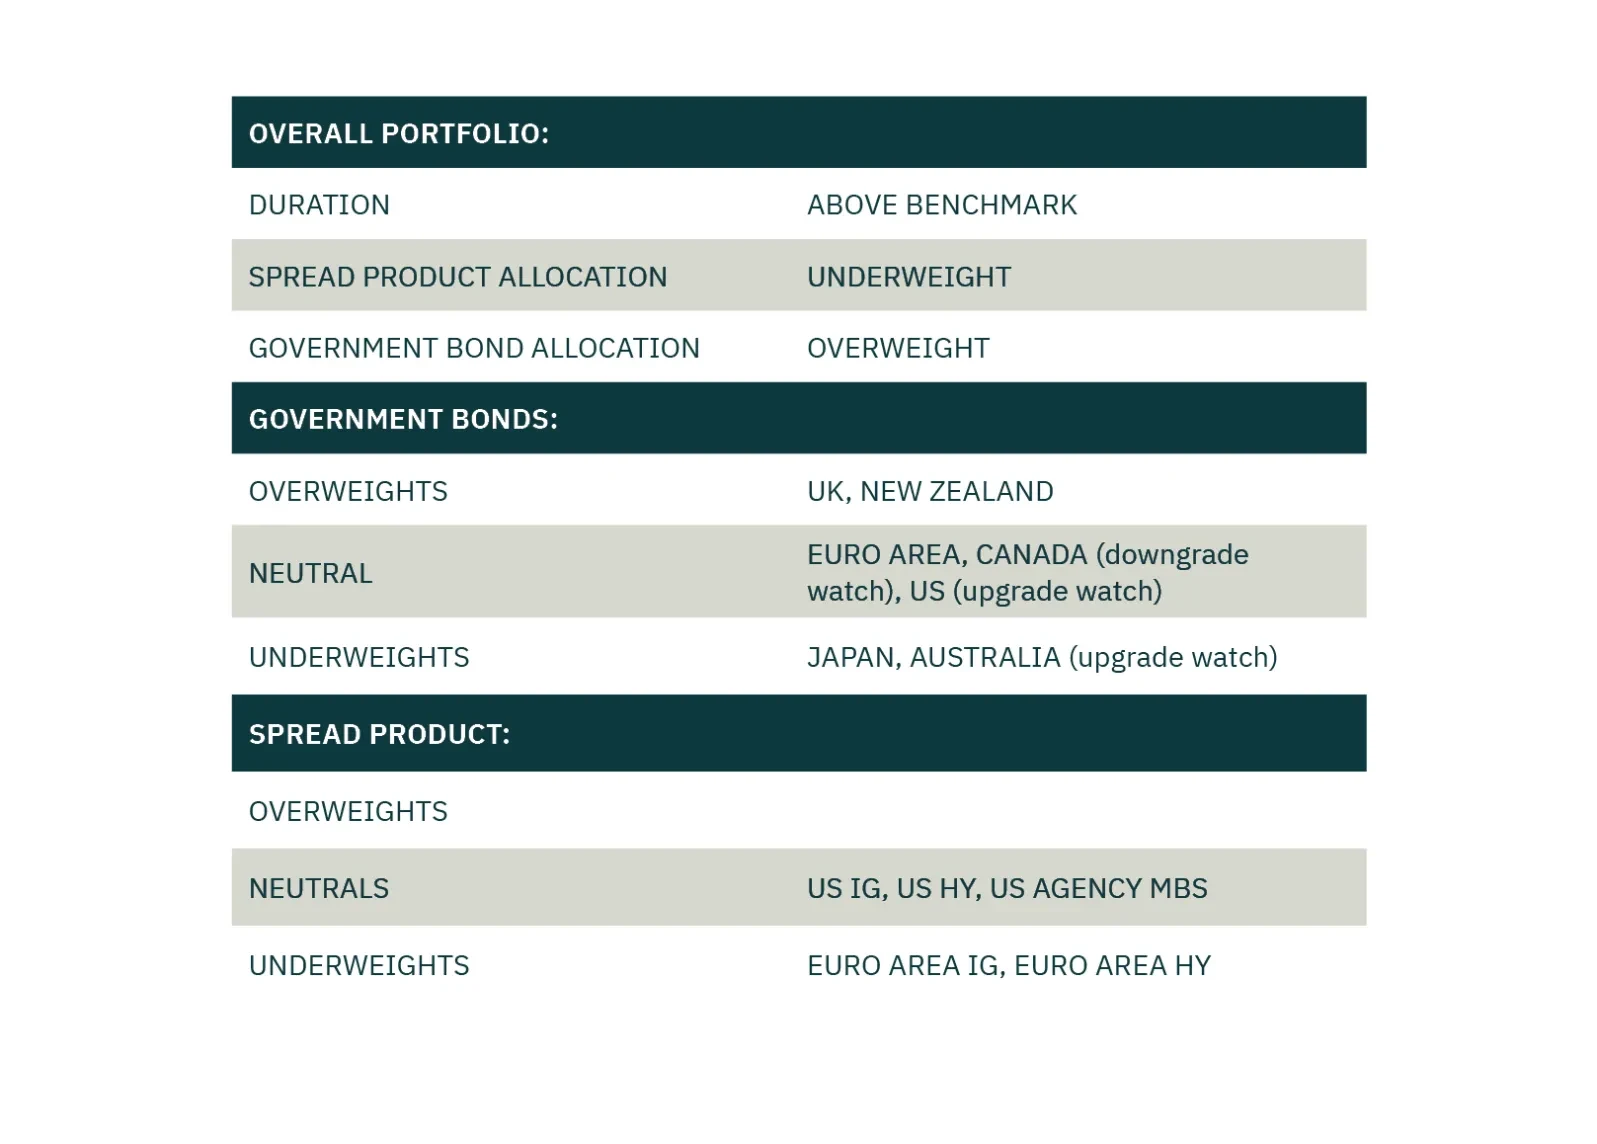
Today, we publish our Quarterly Model Bond Portfolio report. We discuss how the trade war has further increased the global recession risk, but US Treasuries could underperform their global peers in the near term. We cover the fixed income investment implications in the short run and which bond markets are poised to outperform in a severe economic downturn.
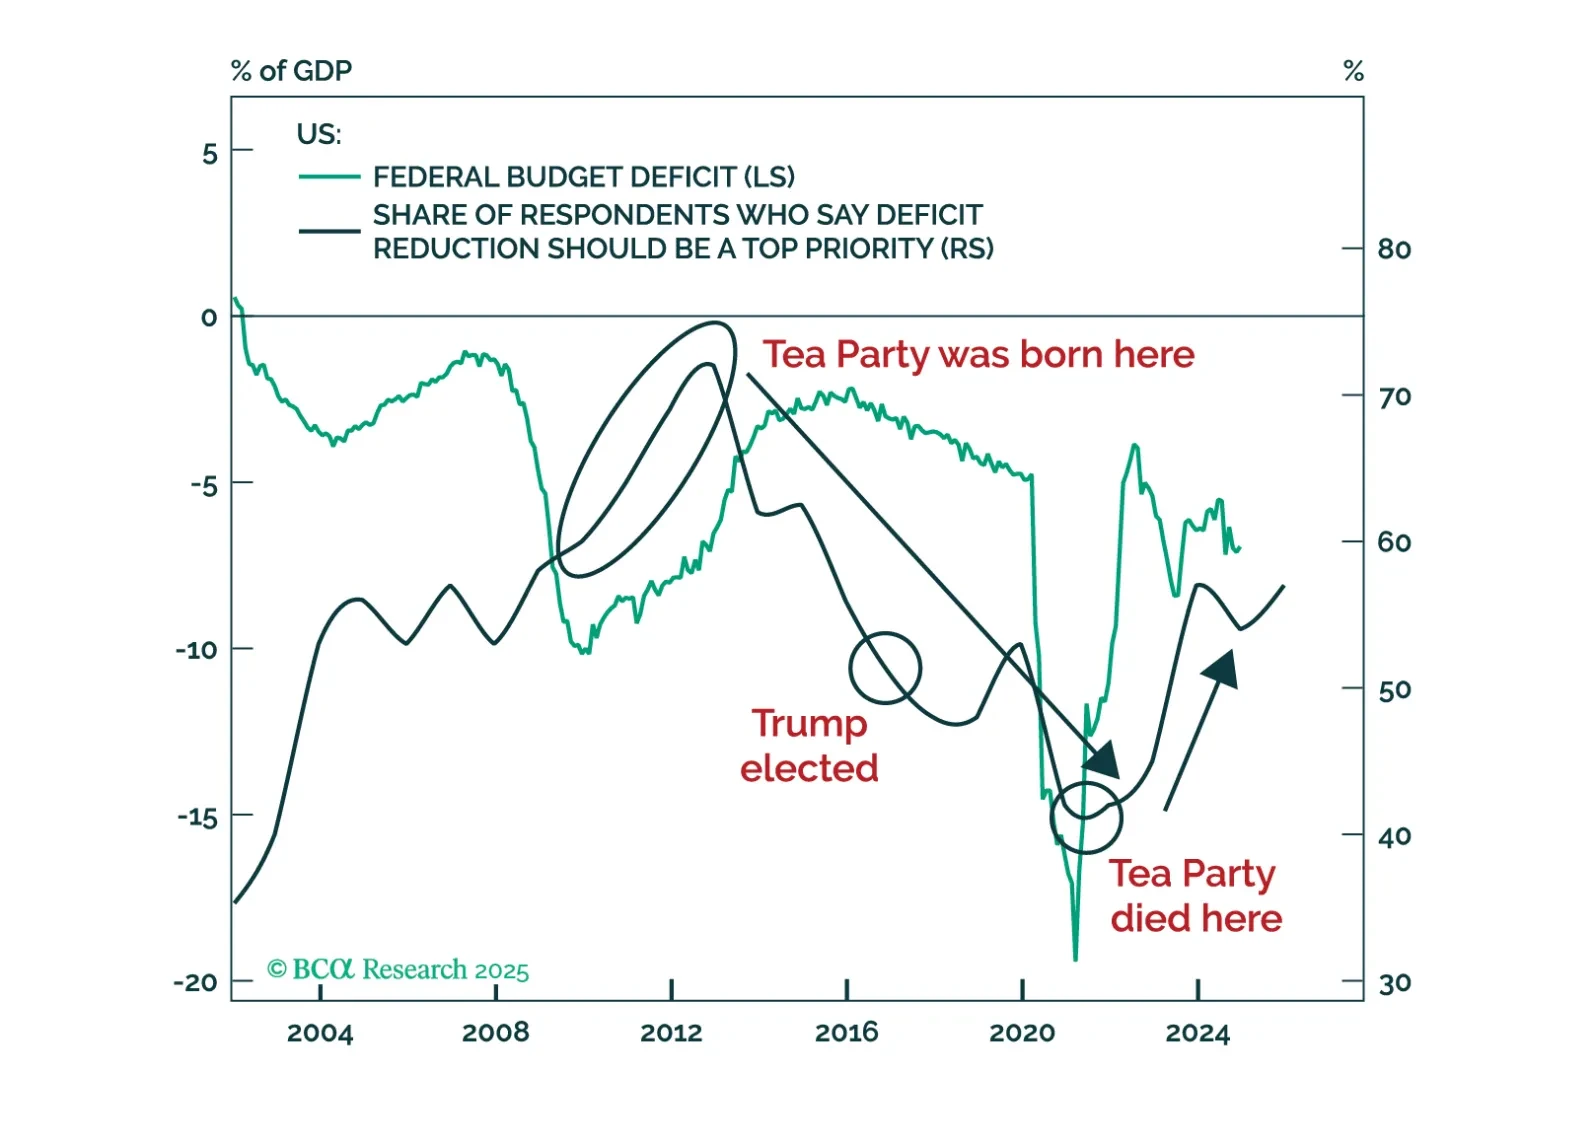
The world is focused entirely on the trade war between the US and… well everyone. This is fair given that there has been no greater market catalyst than Liberation Day since the pandemic. However, we continue to stress that the BIG PICTURE for macro investors is the rotation out of the US. A rotation that started well before April 2, despite the understanding of the investment community that some tariff action would be afoot.
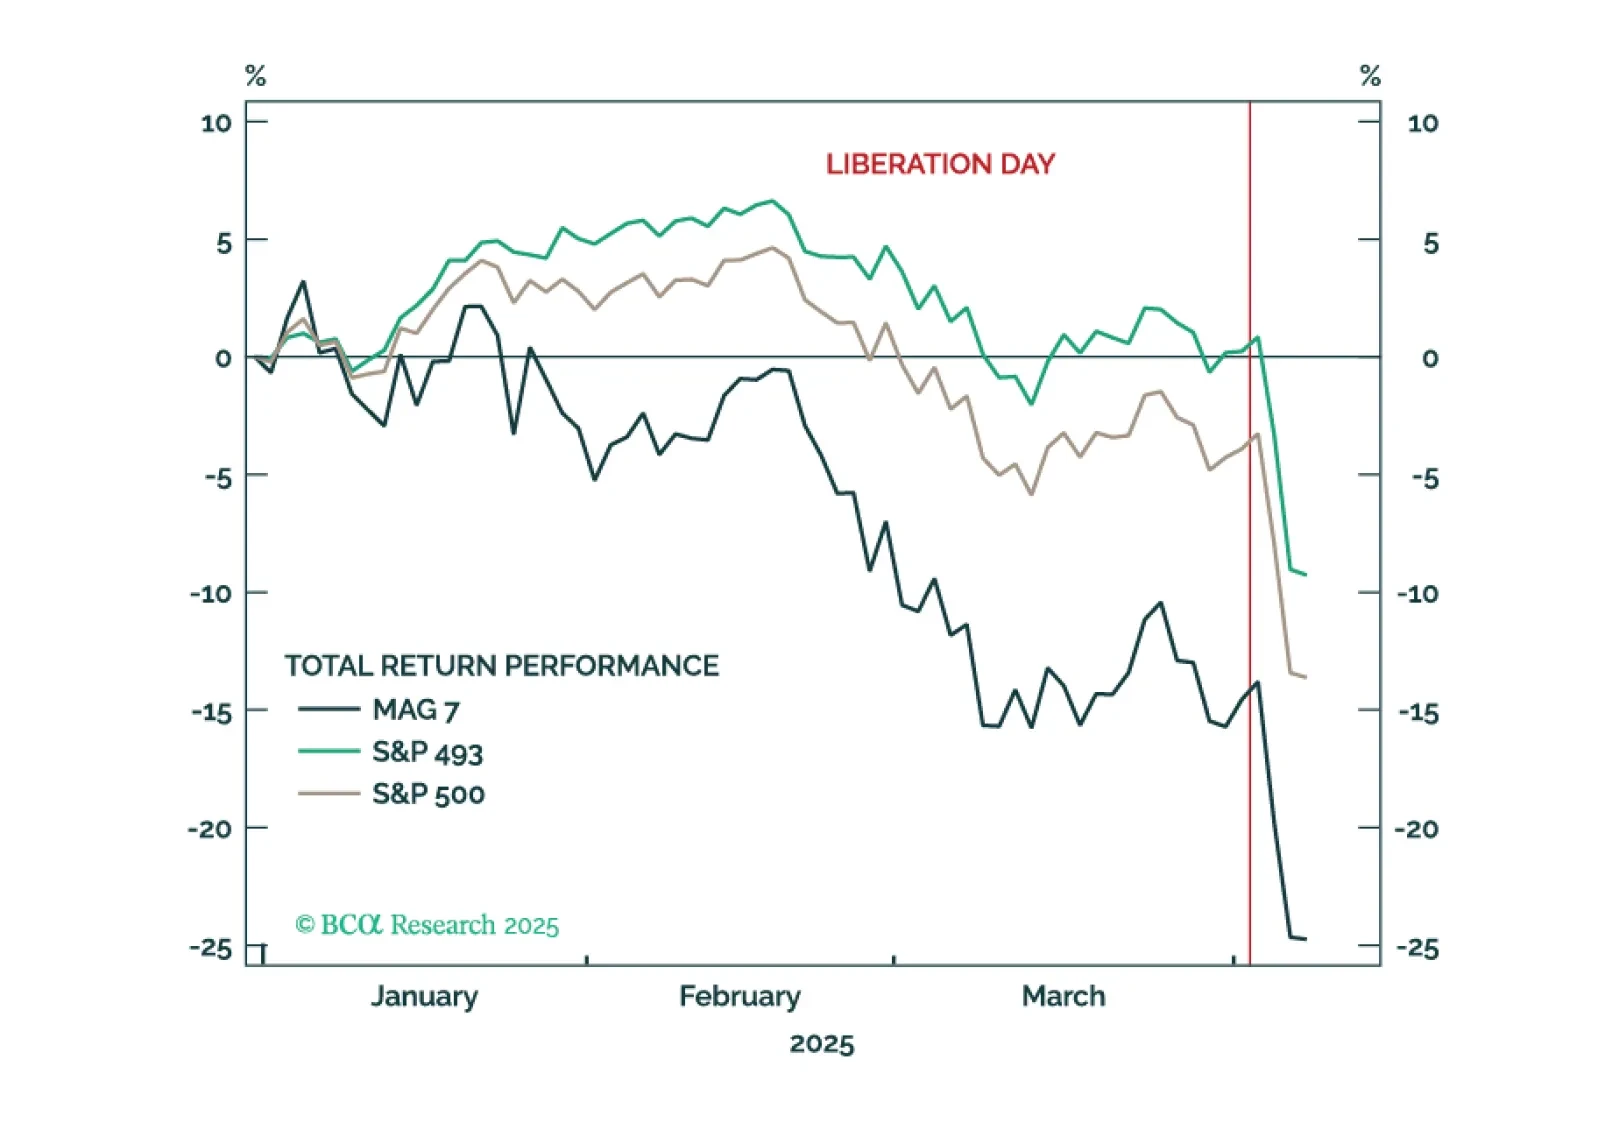
In the front section of the chart pack, we review March’s performance. We will also recommend the portfolio positioning for downward protection.
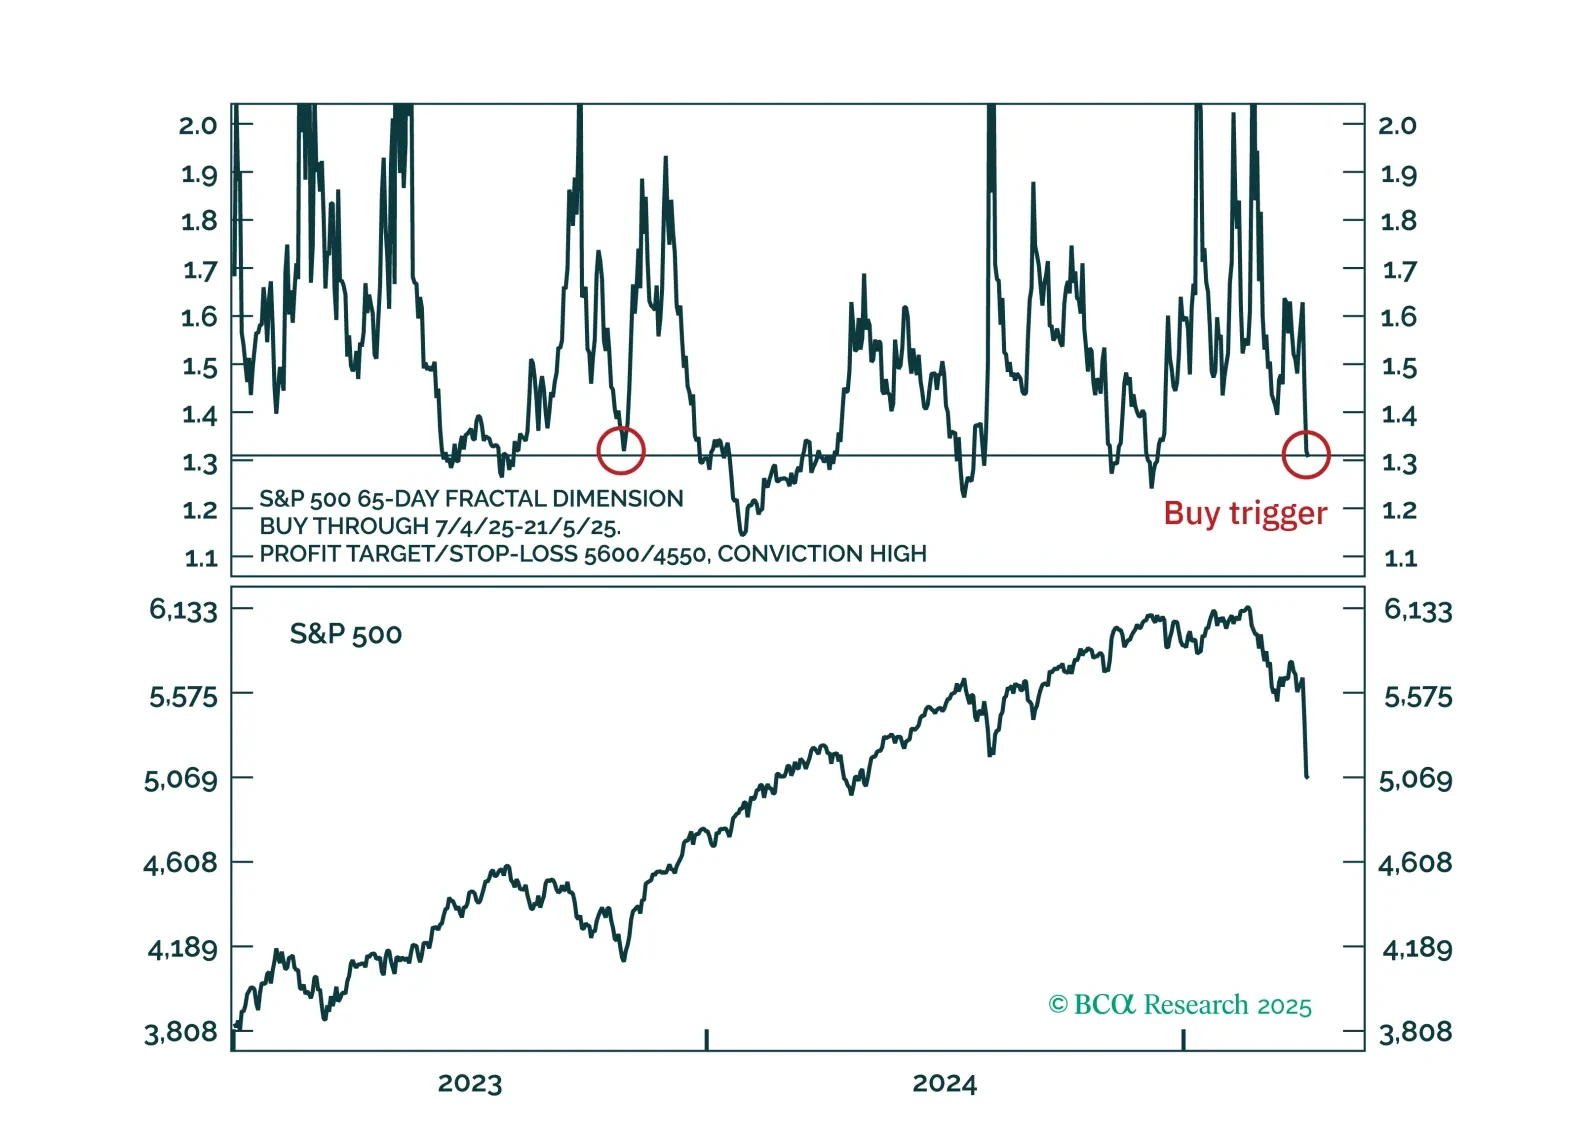
Countertrend buy triggers have been activated for the S&P 500, Nasdaq and Nasdaq versus 30-year T-bond.